Loading...

The Hidden Costs of Maintaining Outdated Banking Software Systems

Every CTO at a bank or NBFC has heard some version of this line in a budget meeting: “The system works fine, why spend money replacing it?” We’ve heard it too, right before a client’s core banking platform went down for six hours during month-end reconciliation and cost them more in penalty interest than a full system upgrade would have.

Legacy banking software rarely fails you loudly. It fails you quietly, month after month, in ways that never show up as a single line item on a budget sheet. That’s exactly what makes it dangerous. At Speqto Technologies, we’ve spent years pulling apart old core banking, lending, and payment systems for BFSI clients, and the same pattern keeps showing up: the “cheap” option of keeping old software alive is usually the most expensive decision on the books.

The maintenance bill nobody budgets for

Old systems don’t get cheaper to run over time — they get more expensive. We worked with a cooperative bank running a core banking system built on a 15-year-old architecture. Their AMC (annual maintenance contract) cost had crept up by nearly 40% over five years, not because the vendor was greedy, but because fewer engineers in the market still understand that codebase. Scarcity drives up the price of every patch, every workaround, every “quick fix.”

Add to that the cost of running parallel infrastructure — old servers that need specific OS versions, hardware that’s no longer manufactured, and licensing fees for software the vendor barely supports anymore. None of this shows up as “technology debt” in a P&L statement. It just quietly eats margin.

Compliance debt piles up faster than you think

RBI’s data localization, reporting, and cybersecurity framework requirements change frequently, and older systems simply weren’t built to flex. We’ve seen NBFCs spend three to four months building manual workarounds — Excel macros, offline reconciliation, human double-checking — just to generate a regulatory report that a modern system would produce in minutes.

That manual patchwork isn’t just slow, it’s risky. One lending client we audited was submitting RBI returns using a process that involved five different spreadsheets and two people cross-checking numbers by hand every quarter. One transposition error away from a compliance flag. The cost of that risk rarely gets calculated until something goes wrong.

The talent problem is real, and it’s getting worse

A lot of Indian banking cores still run on COBOL, older Java frameworks, or heavily customized ERP-style systems from the 2000s. Finding engineers who want to work on these stacks is genuinely hard. The ones who do exist charge a premium, precisely because demand for this dying skill set outpaces supply.

We had a client whose entire loan origination system depended on institutional knowledge held by two senior developers nearing retirement. No documentation, no handover plan. That’s not a hypothetical risk — that’s a bank one resignation letter away from not knowing how its own systems work.

The integration tax on every new initiative

This is the cost that hurts the most in a UPI-driven, API-first market. Every time a bank wants to launch a new digital lending product, plug into an account aggregator framework, or integrate with a fintech partner for co-lending, legacy systems become the bottleneck. What should be a six-week integration turns into a six-month project because the old core wasn’t built with open APIs in mind.

We recently helped a mid-sized NBFC connect their disbursement system to a UPI-based collection partner. On paper it was a standard integration. In practice, we spent nearly half the project timeline building a middleware layer just to translate data formats between their 2009-era core and the fintech partner’s modern REST APIs. That’s not unusual — it’s the norm when legacy meets modern fintech infrastructure.

Security exposure that compounds silently

Older systems often can’t support current encryption standards, multi-factor authentication protocols, or modern intrusion detection without significant retrofitting. Every year they stay in production, the gap between what they can defend against and what attackers can do grows wider. Cyber insurance premiums for BFSI clients running legacy infrastructure have also been climbing — insurers increasingly ask pointed questions about system age during underwriting.

What “it still works” actually costs

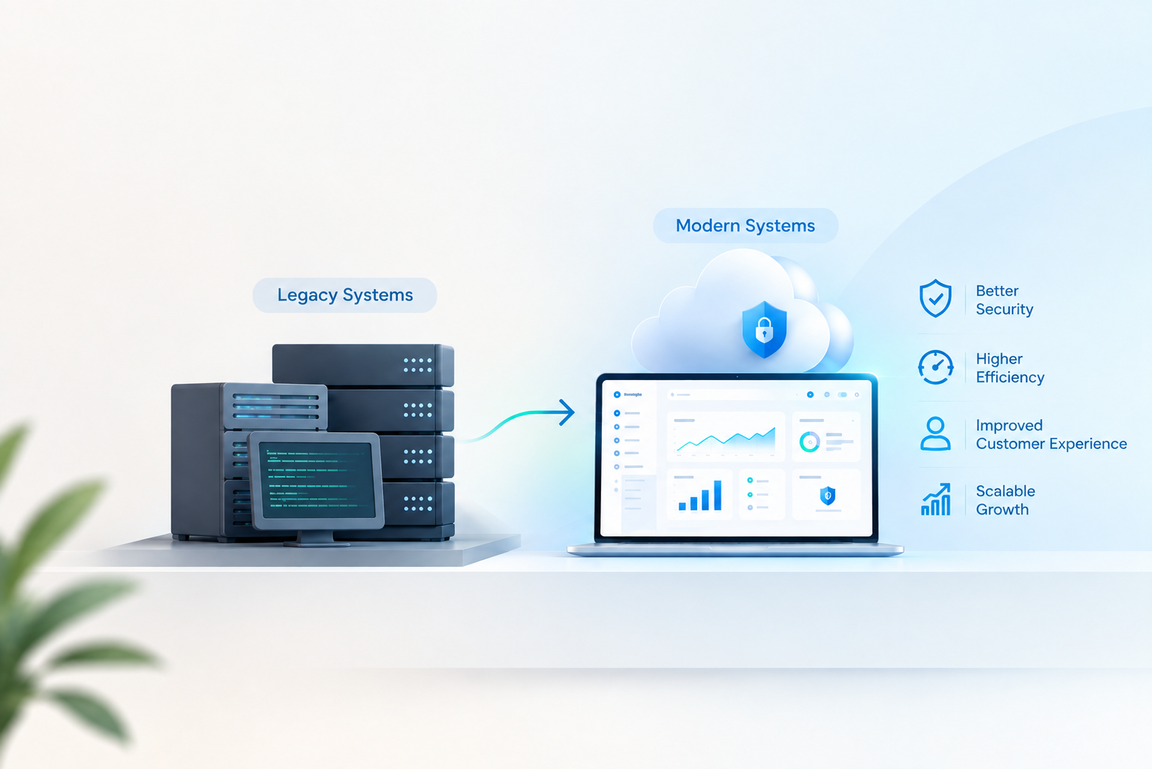
When we sit down with BFSI clients to map out the real cost of legacy systems, it usually breaks into four buckets: rising maintenance and AMC costs, manual compliance workarounds, integration overhead on every new product launch, and the opportunity cost of features competitors ship faster. Individually, each looks manageable. Added up over three or four years, they usually exceed the cost of a phased modernization by a wide margin.

The banks and NBFCs that get ahead of this don’t rip and replace everything overnight — that’s rarely realistic or necessary. They modernize in layers: wrapping legacy cores with modern APIs, migrating high-risk modules first, and building a real roadmap instead of reacting to the next outage. That’s the approach we take with clients at Speqto — not a forklift upgrade, but a plan that respects what still works while fixing what’s quietly costing you money every single month.

If your team has been putting off this conversation because the system “still works,” it might be worth asking a different question: what is it actually costing you to keep it running the way it is?

RECENT POSTS

The Hidden Costs of Maintaining Outdated Banking Software Systems

Every CTO at a bank or NBFC has heard some version of this line in a budget meeting: “The system works fine, why spend money replacing it?” We’ve heard it too, right before a client’s core banking platform went down for six hours during month-end reconciliation and cost them more in penalty interest than a […]
How to Evaluate an IT Services Vendor Before Signing a Contract (A BFSI Playbook)

A few months back, we sat across the table with a mid-sized NBFC that had just walked away from a two-year contract with their previous IT vendor. The reason wasn’t cost. It was that the vendor didn’t understand what “audit trail” meant in the context of RBI’s digital lending guidelines. Six months into the engagement, […]

In-House Team vs IT Outsourcing Partner: What BFSI Leaders Should Actually Weigh Before Deciding

Every CTO or Head of Technology at a bank, NBFC, or fintech eventually hits this question: do we build our own tech team, or do we bring in an outsourcing partner? At Speqto Technologies, we’ve sat on both sides of this conversation – as the partner being evaluated, and as advisors helping clients think through […]

The Real Cost of Delaying Digital Transformation: What Mid-Size BFSI Firms Are Losing Every Quarter

Every mid-size NBFC, cooperative bank, or insurance broker we’ve worked with at Speqto Technologies has, at some point, said some version of the same thing: “We’ll get to the digital overhaul next year, once things settle down.” The problem is, things never settle down. And the invoice for waiting keeps growing quietly in the background […]

How BFSI Companies Can Modernize Legacy Systems Without Disrupting Operations

Every BFSI leader we talk to at Speqto Technologies says some version of the same thing: “Our core system works, but it’s holding us back.” Then in the next breath: “But we can’t afford even four hours of downtime.” That tension between needing to modernize and being terrified of breaking something that processes millions of […]

POPULAR TAG

POPULAR CATEGORIES